Short answer: No. Neither of the last two midterm elections visibly moved Charlotte home prices. In the 12 months after the 2018 midterm, Charlotte-area home values rose 5.9%, and after the 2022 midterm they rose 5.8%.* Mortgage rates fell more than a full point in the first of those years and rose in the second. What changed from one cycle to the next was the pace going in, how fast homes sold and how much was for sale. Those followed mortgage rates and supply, not the election calendar.
Two elections are far too few to prove a pattern either way, so read what follows as context, not a forecast. It covers the Charlotte metro as a whole and single-family homes at $1 Million and above in Mecklenburg County.
Charlotte home values before and after each midterm
The years leading up to the two elections looked very different: +7.7% before 2018 and +17.2% before 2022.* The year after each one landed in nearly the same place. On the latest data, Charlotte-area values were up 1.5% from the second quarter of 2025 to the second quarter of 2026,* and the 30-year rate averaged 7.24% the week of October 29, 2026.**
Sales, days on market and supply: election month vs. one year later
Over the year after the 2018 midterm, the median sale price in the Charlotte metro rose 6.9%, from $245,000 to $262,000. After the 2022 midterm it didn't move at all, holding at $395,000.*** Inventory tightened after both elections: months of supply fell from 2.5 to 1.8 after 2018, and from 1.8 to 1.7 after 2022.***
| Charlotte metro, all homes | Closed sales | Median sale price | Days on market | Months of supply | % of original list price |
|---|---|---|---|---|---|
| Nov 2018 (election month) | 3,049 | $245,000 | 42 | 2.5 | 96.1% |
| Nov 2019 (one year later) | 3,040 | $262,000 | 40 | 1.8 | 96.4% |
| Nov 2022 (election month) | 2,648 | $395,000 | 35 | 1.8 | 95.9% |
| Nov 2023 (one year later) | 2,284 | $395,000 | 31 | 1.7 | 97.1% |
| Sep 2026 (latest report) | 2,776 | $408,000 | 54 | 3.6 | 95.2% |
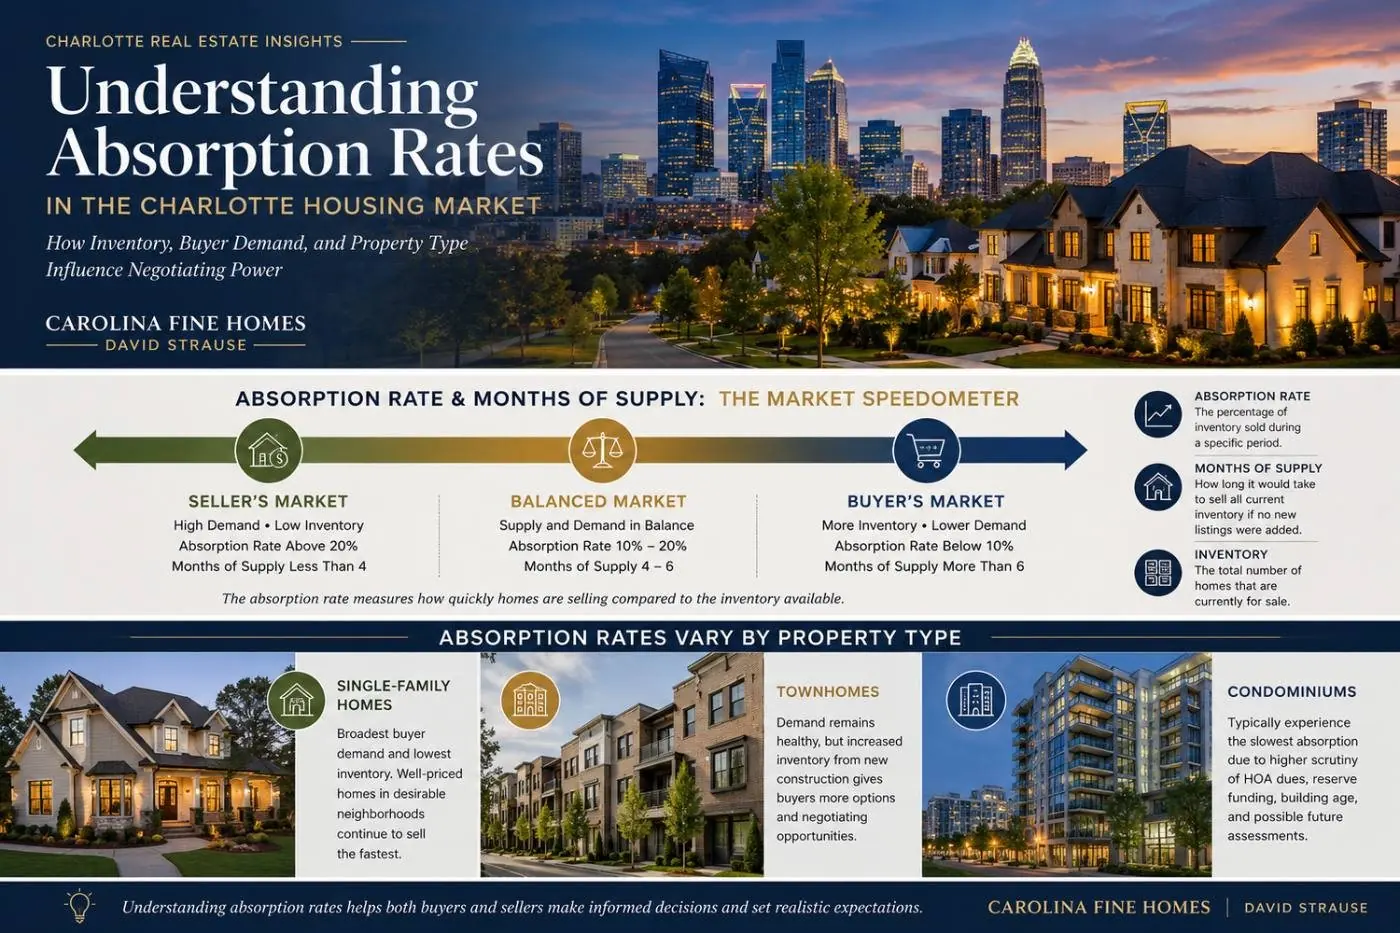
Compared with either election, today's market has about twice the supply, and homes take longer to sell. Going into this midterm, buyers have more room to negotiate than they did in 2018 or 2022.
Homes at $1 Million and above in Mecklenburg County
In the luxury market, the year after each midterm brought more sales and steady prices. Closed sales of single-family homes at $1 Million and above rose 17.8% in the year after the 2018 midterm and 2.2% after 2022. The median sale price moved +1.8% and 0.0%.****
| Mecklenburg County, single-family, $1 Million and above | Closed sales | Median sale price | Median days to contract | Sale price vs. final list price | Months of supply |
|---|---|---|---|---|---|
| Year before the 2018 midterm (Nov 2017 to Oct 2018) | 422 | $1,319,750 | 42 | 96.7% | 9.5 |
| Year after the 2018 midterm (Nov 2018 to Oct 2019) | 497 | $1,343,000 | 35 | 97.3% | 8.6 |
| Year before the 2022 midterm (Nov 2021 to Oct 2022) | 1,067 | $1,400,000 | 4 | 100.0% | 4.4 |
| Year after the 2022 midterm (Nov 2022 to Oct 2023) | 1,090 | $1,400,000 | 5 | 100.0% | 4.4 |
| Most recent year (Nov 2025 to Oct 2026) | 1,614 | $1,484,387 | 9 | 99.6% | 4.9 |
- After 2018, rates fell and luxury buyers came back strongly: 75 more sales than the year before, and homes went under contract a week faster.****
- After 2022, rates topped 7%, yet luxury sales still edged up and homes went under contract in a median of 5 days.**** Buyers at this price point are less dependent on financing, which helps explain why higher rates hit this market less hard than the metro as a whole.
- Today, the luxury market has more supply than in either 2022 period (4.9 months vs. 4.4), and homes take a median of 9 days to go under contract.**** Sales are still rising: 1,614 in the past year, up from 1,511 the year before.****
A note on the median: a fixed $1 Million floor pulls in more homes each year as values rise, which tends to hold the median near the floor. Median prices in this band understate how much individual luxury homes have appreciated, so the metro price index above is the better measure of appreciation.
Mortgage rates: correlation or causation?
Mortgage rates did more to explain each post-election year than the election itself did, but the data shows a correlation, not proof of cause.
| Midterm | 30-year rate, week of the election | 30-year rate, one year later | Change |
|---|---|---|---|
| 2018 | 4.94% (Nov 8, 2018) | 3.69% (Nov 7, 2019) | Down 1.25 points |
| 2022 | 7.08% (Nov 10, 2022) | 7.50% (Nov 9, 2023) | Up 0.42 points |
| 2026 | 7.24% (Oct 29, 2026, latest) | To come |
- After 2018, rates fell more than a full point. Buyers gained purchasing power, sales held steady and the median price rose 6.9%.*** That fits the idea that falling rates support prices.
- After 2022, rates rose past 7%. Closed sales in the election month a year later were down 13.7%, and the median price stayed flat.*** Even so, the price index still rose 5.8%, because very few homes were for sale (1.7 months of supply). Scarce supply held prices up even as higher rates cut into sales.
- The election itself doesn't line up with either pattern. The two post-midterm years moved in opposite directions on rates and sales, yet ended with nearly identical price gains. That points to rates and supply, not the vote, as the forces that mattered.
Why this is correlation and not causation: two cycles are a tiny sample, and other forces moved at the same time, including Federal Reserve policy, job growth and the people moving to the Charlotte region. No one can isolate an election effect from two data points, and this article doesn't claim to.
What this means after the November 3, 2026 midterm
If you've been waiting for the election to pass before you buy or sell, the last two cycles say the vote itself is not the thing to watch. Watch mortgage rates and local inventory.
- Buyers: With 3.6 months of supply and homes taking a median of 54 days to sell,*** you have more choice and more room to negotiate than buyers had after either recent midterm. If rates ease from 7.24%,** more buyers could come back into the market, which would cut into that advantage.
- Sellers: Sellers received 95.2% of original list price in September,*** down from 97.1% a year after the 2022 midterm. A first price set to today's market matters more than when you list relative to the election.
- Everyone: Your neighborhood and price range can behave very differently from the metro median. A home at $1 Million and above in South Charlotte is a different market from the metro as a whole. See the South Charlotte Market Report.
Frequently asked questions
Do home prices drop after a midterm election in Charlotte?
Not after either of the last two. Charlotte-area home values rose 5.9% in the year after the 2018 midterm and 5.8% after the 2022 midterm, based on the FHFA house price index.
Should I wait until after the election to buy a house?
The data does not show an election effect. Mortgage rates and inventory had far more to do with how each post-election year went.
What were mortgage rates during the last midterms?
The 30-year fixed rate averaged 4.94% the week of the 2018 midterm and 7.08% the week of the 2022 midterm, according to Freddie Mac. It averaged 7.24% the week of October 29, 2026.
How much inventory does Charlotte have now?
The Charlotte metro had 3.6 months of supply in September 2026, about double the 1.8 months of November 2022. Homes at $1 Million and above in Mecklenburg County had about 4.9 months of supply.
Did luxury home sales slow after the midterms?
No. Closed sales of Mecklenburg County single-family homes at $1 Million and above rose 17.8% in the year after the 2018 midterm and 2.2% in the year after the 2022 midterm.
What does today's market mean for you?
Elections come and go, and your plans depend on your neighborhood and your price range. If you'd like to know what today's market means for your home or your search, call or text 704-437-2023, or request a private valuation.
Last updated: November 3, 2026.
*Source: U.S. Federal Housing Finance Agency, All-Transactions House Price Index, Charlotte-Concord-Gastonia MSA, quarterly, via FRED (updated August 25, 2026). The index includes appraisal values from refinances as well as sales.
**Source: Freddie Mac Primary Mortgage Market Survey, 30-year fixed-rate average, weeks ending November 8, 2018; November 7, 2019; November 10, 2022; November 9, 2023; and October 29, 2026.
***Source: Canopy MLS via Canopy Realtor Association Local Market Updates, Charlotte MSA, November 2019, November 2023 and September 2026 reports. Prices do not account for sale concessions.
****Source: Canopy MLS, single-family homes in Mecklenburg County that closed at $1,000,000 and above, November 1, 2017 to October 31, 2019; November 1, 2021 to October 31, 2023; and November 1, 2024 to October 30, 2026. Months of supply = active listings in the last month of each period divided by average monthly closed sales in that period. Days to contract is Canopy's days on market. Sale price vs. final list price uses the last list price.
Information deemed reliable but not guaranteed. This article is general information, not financial advice, and does not take any position on any candidate or party.
Related: South Charlotte Market Report · What Is My Home Worth? · Moving to Charlotte · How to Price a Charlotte Luxury Home
Sources: FHFA House Price Index, Charlotte MSA (FRED) · Canopy, November 2019 · Canopy, November 2023 · Canopy, September 2026 · Freddie Mac, November 7, 2019 · Freddie Mac, November 10, 2022 · Freddie Mac, October 29, 2026
David Strause
Broker, Ivester Jackson Christie's International Real Estate · Certified Luxury Home Marketing Specialist · Licensed in NC and SC · 704-437-2023